How digital banking saves time for a Ukrainian entrepreneur
The main demand from entrepreneurs is shifting towards simplicity and automation. According to the global Mastercard Dreamonomics study, small and medium-sized enterprises already use an average of five digital business tools, 89% want to use them even more, and 78% consider the integration of such services with each other to be critical.
The main demand from entrepreneurs is shifting towards simplicity and automation. According to the global Mastercard Dreamonomics study, small and medium-sized enterprises already use an average of five digital business tools, 89% want to use them even more, and 78% consider the integration of such services with each other to be critical.
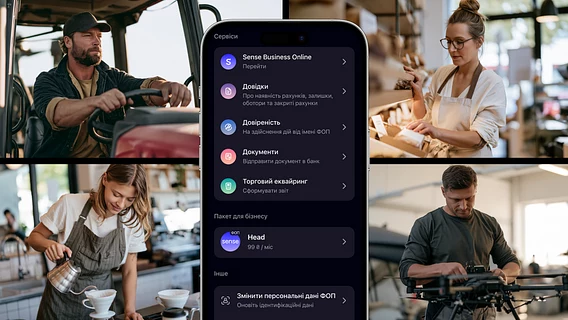
A smartphone has long become a familiar part of an entrepreneur’s work. Now the question is no longer how many functions can be transferred to the application, but how much time they will save. This approach is already clearly visible in Ukrainian banking.
Branchless accounts have become the norm
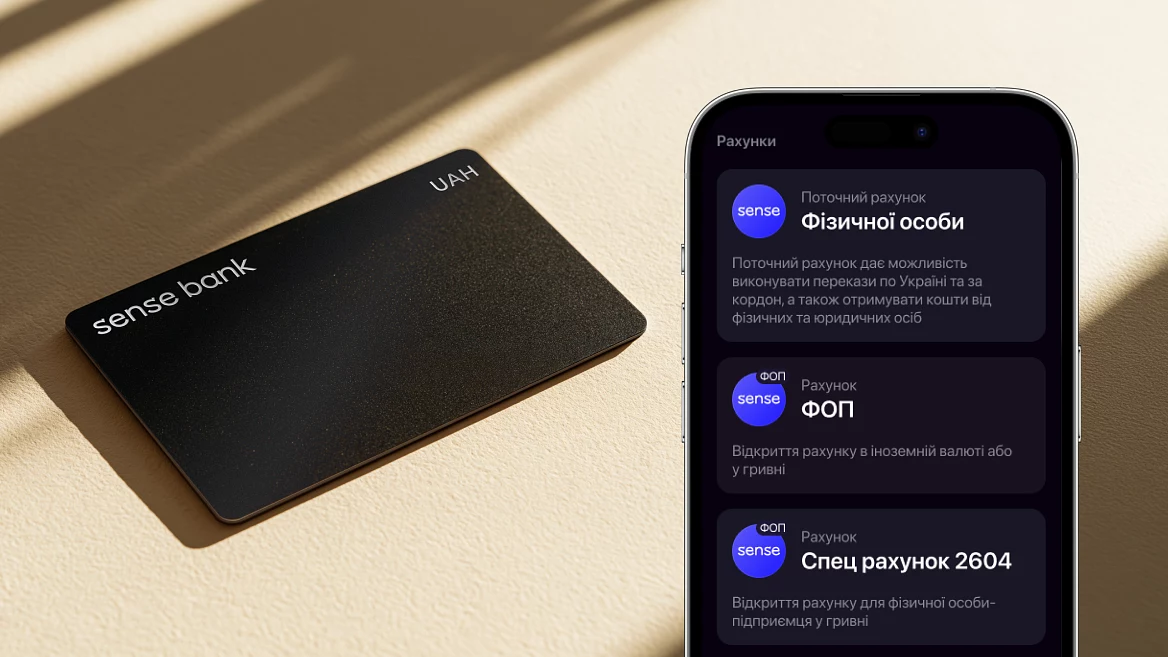
Let’s start with the basic one — opening an account for an individual entrepreneur. If earlier this operation required a visit to the branch, paper documents and time, now it is done in a few clicks from a smartphone over a cup of coffee.
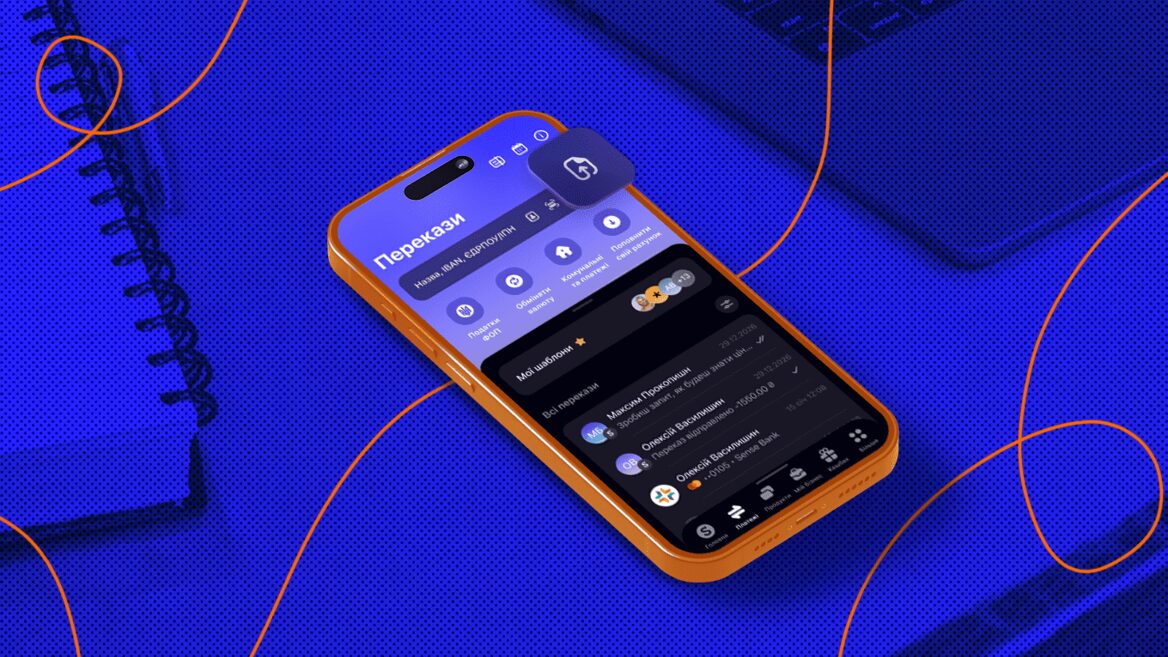
"Ukrainian banks have long introduced account opening completely remotely, and online services are not limited to this. In Sense SuperApp, you can make instant payments and easily pay taxes, transfer individual entrepreneur income to your own card in a few clicks, view the balance and transaction history. And this is just part of the opportunities that are available to an entrepreneur in the application today," comments Yana Shumunova, Director of the Small and Medium Business Department of Sense Bank.
But opening an account is just the beginning. What’s important for an entrepreneur is how convenient it is to use it every day.
Business card in smartphone
According to Mastercard, almost 80% of SMEs in the world already use virtual cards. For Ukrainian businesses, digital financial instruments are of particular importance: the war forced companies to restructure processes more quickly, relocate, and solve more operational issues online.
For example, in Sense SuperApp, you can issue a business card in a few clicks, add it to Apple Pay or Google Pay, and immediately use it for payments: pay for purchases, link the card to business accounts on social networks and other online services to pay for advertising or subscriptions.
Card details, PIN code changes, limits, and blocking are available there as well. That is, the card is gradually becoming not a separate product, but another element of the business expense management system from a smartphone.
AI saves time
Agree, for an entrepreneur, ten or twenty invoices to pay per week are a common situation. Suppliers, rent, advertising, contractors, payment for online services… And each invoice is a 29-character IBAN, an individual personal identification number, the amount and purpose of the payment, which must be manually transferred to banking and checked again before payment.
It is in such small but regular transactions that automation is most noticeable. Sense Bank says that this year they integrated AI into the application to recognize details. Now, to create a payment, it is enough to upload a document, photo or screenshot of the invoice for payment. The system recognizes the data and automatically inserts it into the payment instruction, and the user only has to check the information and confirm the transaction.
For repeated transactions with counterparties, you also don’t need to re-enter data: the application saves history and allows you to copy previous payments with one click.
Bank statements — right in the app
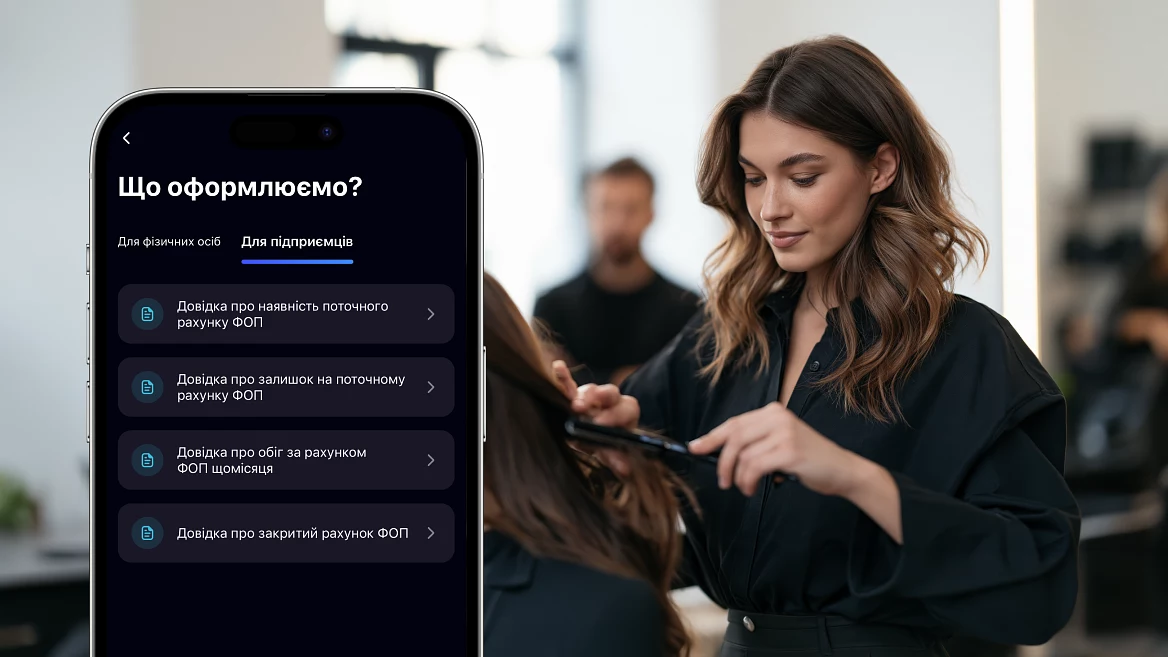
Automation doesn’t just apply to payments. Previously, to obtain a bank statement, an entrepreneur had to separately contact the bank with a request. Now, a statement on account opening, balance status, or turnover for a certain period can be generated online, directly in the application.
The finished document can be immediately downloaded or sent from the application, for example, to the counterparty or institution that requested it, without paperwork and additional appeals to the bank. For an entrepreneur, this means that another typical banking task takes only a few minutes and frees up time for direct business management.
When is automation not enough?
Automation works well for typical tasks. But if the situation is unusual, it is important to be able to quickly contact a manager, rather than looking for an answer in menus and chatbots.
"At Sense Bank, we invest a lot in digitalization because we understand how important it is for an entrepreneur to spend time on strategic issues, not routine," comments Yana Shumunova. "But alongside technological sophistication, we maintain human service. If the situation is non-standard and requires the participation of a specialist, the client can contact a personal manager directly in Sense SuperApp, not a chat bot, and get advice."
Deloitte describes a similar approach: in 2026, simple requests may increasingly be transferred to self-service using AI, while complex and sensitive situations should still remain with a human.